What Happens During a Davis-Bacon Audit
— WH347.io Team
Prepare for a Davis-Bacon records request with payroll, time, classification, fringe, and subcontractor evidence. Understand access duties and potential remedies without assuming an audit timetable or outcome.
DOL's Wage and Hour Division has authority to investigate DBRA compliance, and contracting agencies have day-to-day administration and enforcement duties. Complete records help you respond, but they do not guarantee a finding or make an investigation merely a paperwork exercise. This guide does not establish a recent enforcement trend.
What Triggers a Davis-Bacon Audit?
- Worker complaint — workers can raise concerns about underpayment or misclassification with WHD; the cited sources do not rank complaint frequency.
- Routine compliance review by the contracting agency — federal agencies are required to monitor contractor compliance and may refer cases to the DOL.
- Referral from the contracting officer — if the agency notices missing or irregular certified payroll submissions, they may escalate to WHD.
- Missing or incomplete certified payrolls — submission and recordkeeping failures are compliance issues, not proof of a published automatic audit trigger.
- Other reported concerns — evaluate the facts rather than assuming a complainant's motive or an automatic investigation outcome.
What Do Auditors Actually Look At?
The underlying records and access duties are set out in 29 CFR 5.5(a)(3). Follow our retention checklist and retain evidence of plan contributions and cash fringe payments, not just the completed forms.
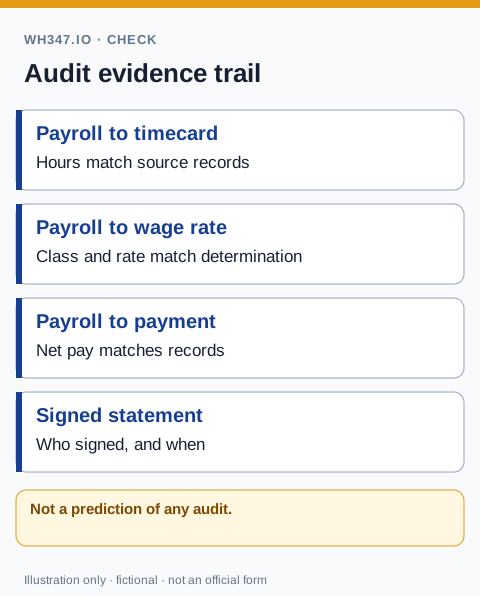
The Wage and Hour Division will issue a request for records covering the audit period. Their job is to compare what you reported on the WH-347 against your actual payroll practice. Discrepancies — intentional or not — are what they're looking for.
- Certified payrolls and signed compliance statements for every week with covered work; include additional no-work reports only where the agency or contract requires them.
- Payroll registers or records showing actual wages paid to each worker.
- Daily time and attendance records — hours worked each day, by worker, including any overtime.
- Worker classification documentation — evidence of what each worker actually did on site and the wage determination that applied.
- Fringe benefit documentation — insurance statements, pension remittance records, or cash-in-lieu calculations.
- Subcontractor certified payroll records, if you are the prime contractor — auditors will want to see subs' compliance too.
How Long Does an Audit Take?
The sources cited here do not prescribe a standard investigation duration or a universal two-year DBRA recovery limit. Scope, records, disputed classifications, and the applicable legal claim affect the process. Ask the investigator about requested records and deadlines, and consult counsel about any limitation period; do not use an assumed recovery limit to shorten mandatory record retention.
What Are the Penalties?
- Unpaid wages — an underpayment can require payment of amounts owed to affected workers, with contract funds withheld to satisfy liabilities.
- Debarment — DOL Fact Sheet 66 describes possible exclusion from future contracts for three years, subject to the applicable determination and appeal process.
- Contract termination — the contracting agency may terminate your contract if violations are serious enough.
- CWHSSA liquidated damages — applicable overtime violations have a separate damages provision; this is not a universal doubling of DBRA back wages.
- Criminal referral — in cases involving falsified Statements of Compliance or deliberate fraud, the DOL can refer the matter for criminal prosecution.
The Most Common Violations Auditors Find
- Misclassification — workers doing skilled trade work listed under a lower-paid classification on the WH-347.
- Underpayment — base wages below the applicable prevailing wage rate for the project location and trade.
- Missing or incomplete fringe benefit payments — failing to pay the fringe component of the wage determination.
- Falsified or inconsistent records — WH-347 figures that don't match payroll registers or time records.
- Failure to submit WH-347 weekly — gaps in submission history or chronic lateness.
How to Prepare Before an Audit Happens
The contractors who move through audits cleanly are the ones who treat record-keeping as a routine part of every project — not an emergency response. Here's what that looks like in practice:
- Preserve basic records, certified payrolls, and contract documents during the work and for at least three years after all prime-contract work is completed. This is a regulatory requirement, not a recommended buffer; check longer obligations and preservation holds.
- Verify worker classifications against the wage determination at the start of every project. The classification must match the work performed, not just the job title.
- Reconcile your WH-347 submissions against your actual payroll each week as you go. Catching an error in week 3 is far easier than reconstructing months of records during an investigation.
- Keep fringe benefit documentation current — insurance premium statements, pension remittance confirmations, and cash-in-lieu calculations all need to be on file.
- Make sure every subcontractor on your project is submitting their own certified payroll on schedule. As prime, their compliance is your problem.
What to Do If You're Contacted by the DOL
Do not ignore a WHD inquiry. Preserve the requested records, organize them by project and week, and consider qualified legal advice. Section 5.5(a)(3)(iv) requires access to records and worker interviews and provides sanctions for noncompliance. Ask promptly for a reasonable extension if needed; WHD considers such requests. Discuss any discrepancies with counsel without assuming voluntary correction guarantees a particular outcome.
How WH347.io Keeps You Audit-Ready
WH347.io can help organize project, employee, and timecard data used to prepare reports. Keep a separate archive of the exact submitted versions, signed certifications, payment evidence, and supporting documents. A report regenerated from current data is not proof of what was signed or submitted previously, and an account is not a substitute for your retention obligations.
A records request does not itself establish a violation. A consistent weekly review and complete supporting records help you respond, but no software or filing practice guarantees compliance or an investigation outcome.
Frequently Asked Questions
What triggers a Davis-Bacon audit?
Worker complaints and agency compliance reviews can lead to investigation. Missing payrolls, underpayment concerns, and classification issues merit review. The official sources cited here do not rank triggers or establish an automatic audit-selection formula.
What records do auditors request in a Davis-Bacon audit?
Required records include certified payrolls for weeks with covered work and signed compliance statements, actual payroll and time records, classifications, fringe and apprentice evidence, and contract documents. Primes should also keep required subcontractor payrolls. Any additional no-work filing depends on agency or contract instructions.
How long does a Davis-Bacon audit take?
There is no standard duration established by the cited guidance. Ask the investigator about scope and deadlines. This guide does not establish a universal two-year DBRA recovery limit; obtain advice about the applicable claim and preserve records for the required retention period regardless.
What are the penalties for Davis-Bacon violations found during an audit?
Possible remedies include unpaid wages, withholding, contract termination, and three-year debarment. CWHSSA overtime liquidated damages are separate, not an automatic doubling of DBRA back wages. Falsified certifications may lead to civil or criminal prosecution. Outcomes depend on the facts and applicable law.
How long must certified payroll records be kept?
Federal DBRA rules require records during the work and for at least three years after all work on the prime contract is completed. This is a mandatory retention period, not a recommended buffer. Check state, grant, contract, and preservation requirements for any longer obligation.